Did you know that nearly 70% of Americans admit they do not fully grasp the fine print of their financial protection agreements? This gap in knowledge often leads to unexpected out-of-pocket costs during a crisis. Navigating complex insurance terminology can feel like learning a foreign language, but it does not have to be that way.
Our goal is to make these insurance policy terms explained in a way that empowers you to review your coverage with total confidence. We break down confusing jargon into simple, actionable advice. You will learn how to manage your premiums, deductibles, and coverage limits without the headache of legal speak.
By mastering these basics, you gain the freedom to choose the right protection for your family. Let us simplify your contracts so you can focus on what truly matters.
Key Takeaways
- Learn to decode complex industry jargon into simple language.
- Understand how deductibles and premiums impact your monthly budget.
- Discover the importance of knowing your specific coverage limits.
- Identify common exclusions that might leave you vulnerable.
- Gain the confidence to manage your financial protection agreements effectively.
Insurance Policy Terms Explained in Plain English
Navigating the world of insurance can feel like learning a foreign language. When you receive your policy documents, the sheer volume of policy definitions can seem overwhelming. However, having this insurance jargon explained clearly allows you to take control of your financial protection.
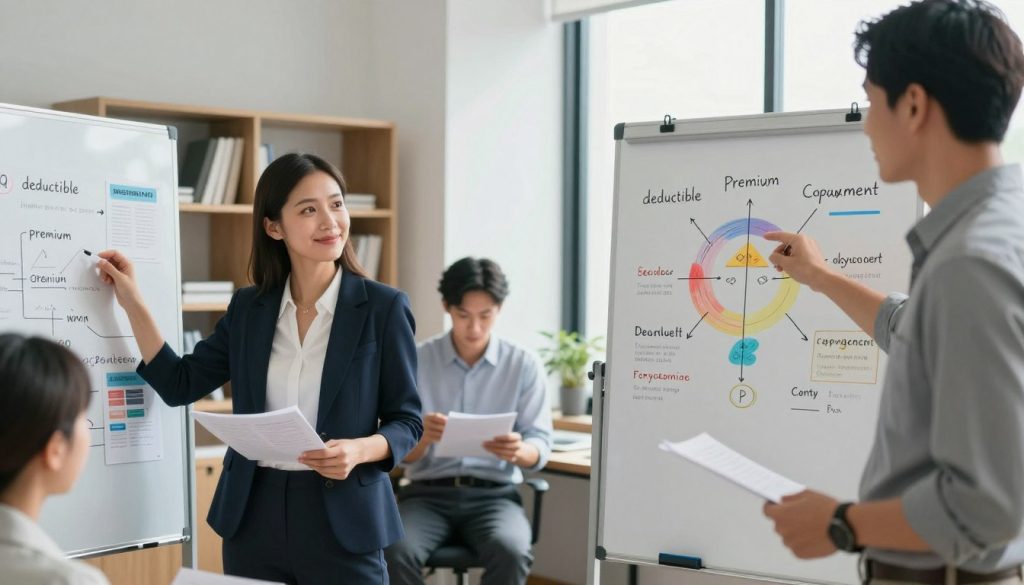
Premium, Deductible, and Policy Limit
How the Premium Affects What You Pay
The premium is the amount you pay to the insurance company to keep your policy active. Think of it as the subscription fee for your peace of mind. Higher coverage amounts or lower deductibles usually lead to a higher premium.
How a Deductible Changes Claim Costs
A deductible is the portion of a loss you agree to pay out of your own pocket before the insurer covers the rest. Choosing a higher deductible often lowers your monthly premium costs. It is a balancing act between immediate savings and potential future expenses.
Why Policy Limits Matter
The policy limit represents the maximum amount an insurance company will pay for a covered loss. If your damages exceed this limit, you are responsible for the remaining balance. Always ensure your limits align with the total value of your assets.
Coverage, Perils, and Exclusions
Covered Perils and Insured Events
A peril is a specific cause of loss, such as fire, theft, or windstorm. Your policy lists which perils are covered under your agreement. Understanding these events helps you identify where you have true protection.
Exclusions That Remove Protection
Exclusions are specific situations or items that your policy does not cover. Common examples include intentional damage or wear and tear. Reviewing these sections is vital to avoid surprises during a claim.
Additional Coverage and Optional Protection
Sometimes, standard policies do not cover everything you need. You can purchase endorsements or riders to add extra protection for high-value items like jewelry or specialized equipment.
Policyholder, Insured, Beneficiary, and Additional Insured
Who Owns the Policy and Who Receives Benefits
The policyholder is the person who owns the contract and pays the premiums. The insured is the person or entity protected by the policy. In life insurance, the beneficiary is the individual designated to receive the payout upon the death of the insured.
When an Additional Insured Has Limited Protection
An additional insured is a person or organization added to a policy to receive coverage for specific risks. This is common in business contracts or rental agreements. They typically have limited rights compared to the primary policyholder.
| Term | Primary Function | Financial Impact |
|---|---|---|
| Premium | Cost of coverage | Recurring expense |
| Deductible | Out-of-pocket cost | Reduces claim payout |
| Policy Limit | Maximum payout | Caps insurer liability |
| Exclusion | Non-covered risk | Zero coverage provided |
Insurance Policy Provisions and Coverage Details to Review
Your insurance policy is a legal contract that dictates exactly how and when you receive financial protection. Taking the time to perform an insurance terms breakdown allows you to see the full scope of your protection before an emergency occurs.
The Declarations Page and Insuring Agreement
Finding the Named Insured, Coverage Dates, and Limits
The declarations page acts as the summary of your entire policy. It lists the named insured, which is the person or entity covered by the contract. You will also find the specific policy period, including start and end dates, along with the maximum dollar limits for each type of coverage.
Understanding the Insurer’s Promises to Pay
The insuring agreement outlines the core promise made by your insurance company. It defines the scope of protection and the specific events that trigger a payout. Always verify that these promises align with your expectations for financial security.
Conditions, Duties, and Claim Requirements
Notice of Loss and Proof of Loss
Policy conditions are the rules you must follow to keep your coverage active. When a loss occurs, you are typically required to provide prompt notice to the insurer. You must also submit a formal proof of loss, which is a detailed statement documenting the damage and the value of the claim.
Cooperation, Documentation, and Loss Prevention
You have a duty to cooperate with your insurer during the investigation process. This includes providing receipts, photos, and other relevant documentation. Furthermore, you are expected to take reasonable steps to prevent further damage to your property after an incident.
How Policy Conditions Can Affect a Claim
Failure to meet these conditions can lead to a denied claim or reduced payout. It is vital to understand these requirements early to ensure you remain in compliance with your contract.
Actual Cash Value, Replacement Cost, and Liability Coverage
Actual Cash Value Versus Replacement Cost
Understanding how your items are valued is a critical part of having your insurance coverage explained clearly. The following table highlights the key differences between these two common valuation methods:
| Feature | Actual Cash Value (ACV) | Replacement Cost |
|---|---|---|
| Definition | Current market value | Cost to buy new |
| Depreciation | Includes depreciation | No depreciation |
| Payout | Lower amount | Higher amount |
How Liability Coverage Responds to Third-Party Claims
Liability coverage protects you when you are legally responsible for injury or damage to others. It covers legal defense costs and settlements up to your policy limit. This is essential for protecting your personal assets from lawsuits.
Subrogation, Coordination of Benefits, and Other Contract Terms
Subrogation allows your insurer to pursue a third party who caused your loss to recover the money they paid you. Coordination of benefits ensures that if you have multiple policies, they work together without paying you more than the total loss amount.
Endorsements, Renewals, Cancellations, and Grace Periods
How Endorsements Change Standard Policy Language
An endorsement is a written amendment that changes the terms of your original policy. These can add specific coverages, remove exclusions, or adjust your limits. Always review these carefully, as they override the standard language in your main contract.
What Renewal and Cancellation Notices Mean
Renewal notices inform you of changes to your premium or coverage for the upcoming term. Conversely, a cancellation notice indicates that your policy will end on a specific date. If you miss a payment, a grace period may allow you a short window to pay your premium before the policy officially lapses.
Conclusion
Navigating the world of coverage requires a clear grasp of how your protection works. With these policy provisions demystified, you gain the confidence to manage your financial future effectively.
You now hold the tools to evaluate your specific needs. Having your policy language deciphered allows you to spot gaps in your current plan. You can now assess your premiums, deductibles, and limits with total clarity.
Take a moment to review your declarations page and current endorsements. This proactive step ensures your insurance contract terms clarified through this guide remain aligned with your life goals. Companies like State Farm or Geico offer resources to help you verify these details.
Check your claim duties and renewal dates today. Staying informed protects your assets and provides peace of mind. Reach out to your agent if you have questions about your specific coverage.
## FAQ
### Q: What is the main difference between a premium and a deductible?
A: Think of the premium as your “membership fee” for the insurance policy; it is the regular amount you pay to companies like Progressive or State Farm to keep your coverage active. The deductible is the specific amount you agree to pay out-of-pocket before your insurance company steps in to cover a claim. Understanding these insurance policy terms explained helps you decide if you prefer lower monthly costs or lower costs at the time of an accident.
### Q: Why are policy limits so important to review?
A: A policy limit is the maximum amount your insurer will pay for a covered loss. For example, if you have a $50,000 liability limit with Allstate but cause $75,000 in damages, you could be responsible for the $25,000 difference. Reviewing these policy definitions ensures you have enough financial protection to cover your actual assets and potential risks.
### Q: What is the difference between a covered peril and an exclusion?
A: In standard insurance terminology, a peril is a specific event that causes damage, such as a fire, windstorm, or theft. An exclusion is a specific situation or cause of loss that the policy explicitly states it will not cover. Having your insurance coverage explained in this way makes it easier to see that while Liberty Mutual might cover a fire, they may exclude damage from normal wear and tear or intentional acts.
### Q: How do Actual Cash Value and Replacement Cost affect my claim payout?
A: This is a crucial part of having policy provisions demystified. Actual Cash Value (ACV) pays you what an item is worth today, which includes a deduction for depreciation (wear and tear). Replacement Cost pays the actual dollar amount it takes to buy a brand-new version of the item at today’s prices. Most consumers find that having this policy language deciphered helps them choose the coverage that provides the best long-term value.
### Q: What are endorsements and how do they change my coverage?
A: An endorsement, also known as a rider, is an amendment to your policy that adds, deletes, or changes your coverage. For instance, you might add an endorsement to a USAA policy to provide extra protection for high-value jewelry. These insurance contract terms clarified allow you to customize a standard policy to fit your unique personal needs.
### Q: What should I look for on my insurance Declarations Page?
A: Your Declarations Page is a one-to-two-page summary that provides an insurance terms breakdown for your specific account. It lists the named insured, the policy period, your specific coverage limits, and the premiums for each type of protection. It is the best place to start when you want to see exactly what you are paying for without digging through the entire legal contract.
### Q: What do “subrogation” and “coordination of benefits” mean in plain English?
A: These are common examples of insurance jargon explained. Subrogation is the process where your insurance company pays for your loss and then legally pursues the “at-fault” party to recover the funds. Coordination of benefits is a process used when you have more than one insurance policy, ensuring that the companies work together to pay the claim correctly without duplicating payments.
### Q: What happens during the grace period of a policy?
A: The grace period is a set number of days after your premium due date during which you can still make a payment without your coverage lapsing. Knowing this part of your insurance terminology can be a lifesaver if you accidentally miss a payment deadline with a carrier like Geico, as it prevents you from being uninsured during that short window.